

Hi hunters,
Apologies for the delay.
Struck by sickness, I’m having a hard time going through all the earnings. 4 articles are sitting in the draft folder, so expect to have several sent to you in the next 2 weeks.
Let’s take a look at the first company we want to cover this earnings season: I-TECH.
Company: I-Tech AB · Ticker: ITECH (Nasdaq First North Growth Market, Stockholm) · Share price: 59.9 SEK (29 Oct 2026) · Market cap: 718.7m SEK
Original write-up: 55% revenue growth, 158% expected return. I’m buying. (30 May 2025). Previous update: 3Y Sales CAGR of 48%: Code Cracked (14 September 2025).
The business did what I wanted it to do. Net sales grew +19.0% to SEK 48,763k, 18% of that organic, gross margin 60% against 57% a year ago.
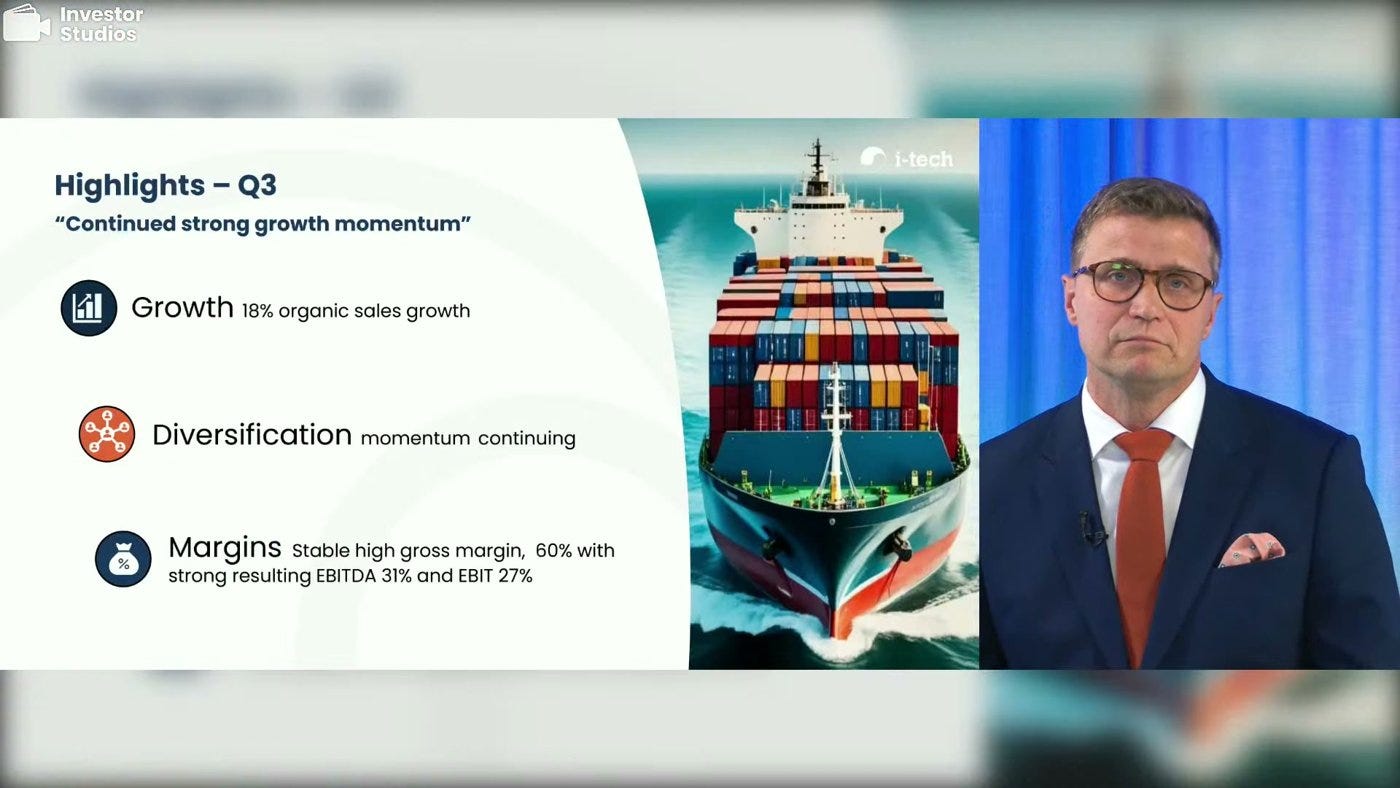
The customer whose financial trouble wrecked 2025, the one I named as my reason for not adding last September, is back and growing 123% year-to-date. The product diversification I’ve asked for since the original pitch arrived twice in three months.
So why am I not buying?
Because between the 7th and the 21st of October, EU member states voted by written procedure on the Commission’s proposal not to renew medetomidine, the active substance in Selektope. The decision normally lands one to two weeks after the vote closes, and the current EU approval expires at the end of this year.
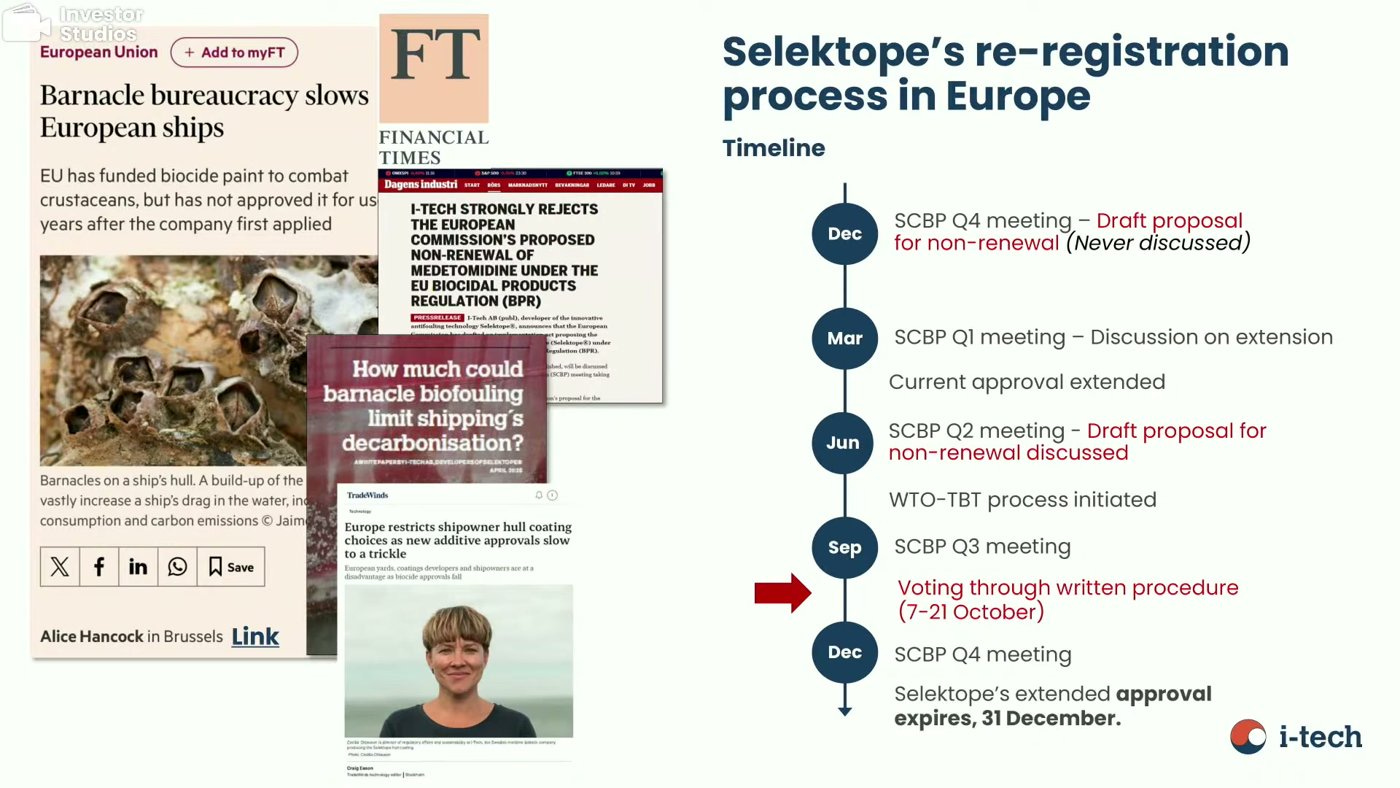
The direct revenue at stake is small. It’s more reputational risk and what their customers in Asia will do as a result.
Full analysis ⬇️
Financial performance
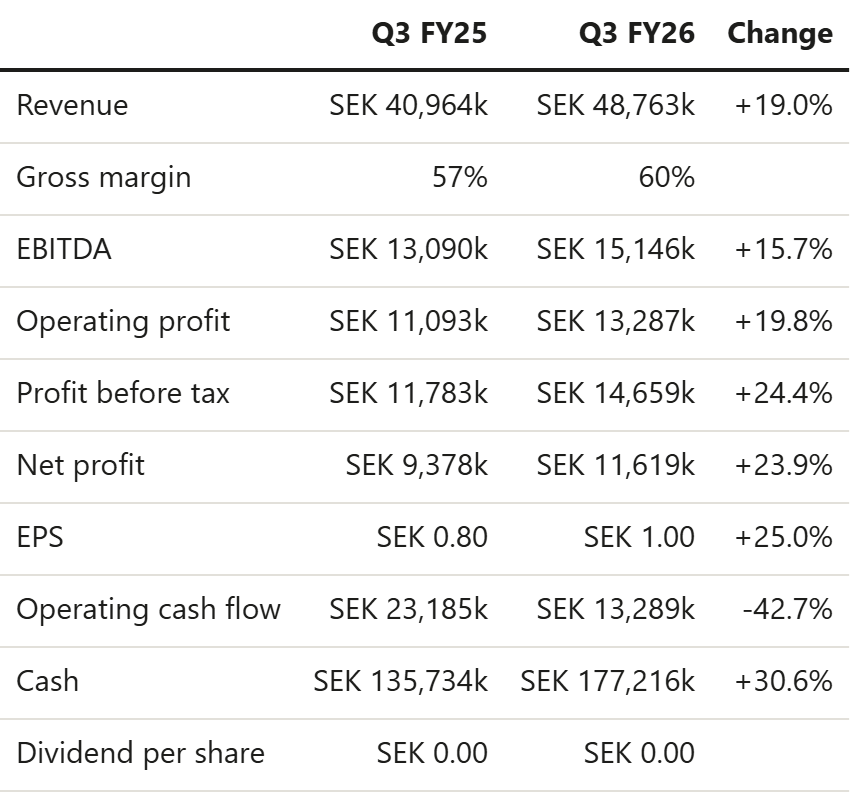
This table looks the way I hoped the 2025 tables would look. Revenue up, gross margin up 300 basis points, operating profit up +19.8%, net result up +23.9%, EPS from SEK 0.80 to SEK 1.00.
However.
Operating cash flow fell -42.7% to SEK 13,289k. This isn’t a deterioration in the business: the report blames trade receivables, and the call added that Q3 2025 was flattered by collections on a very weak Q2 2025.
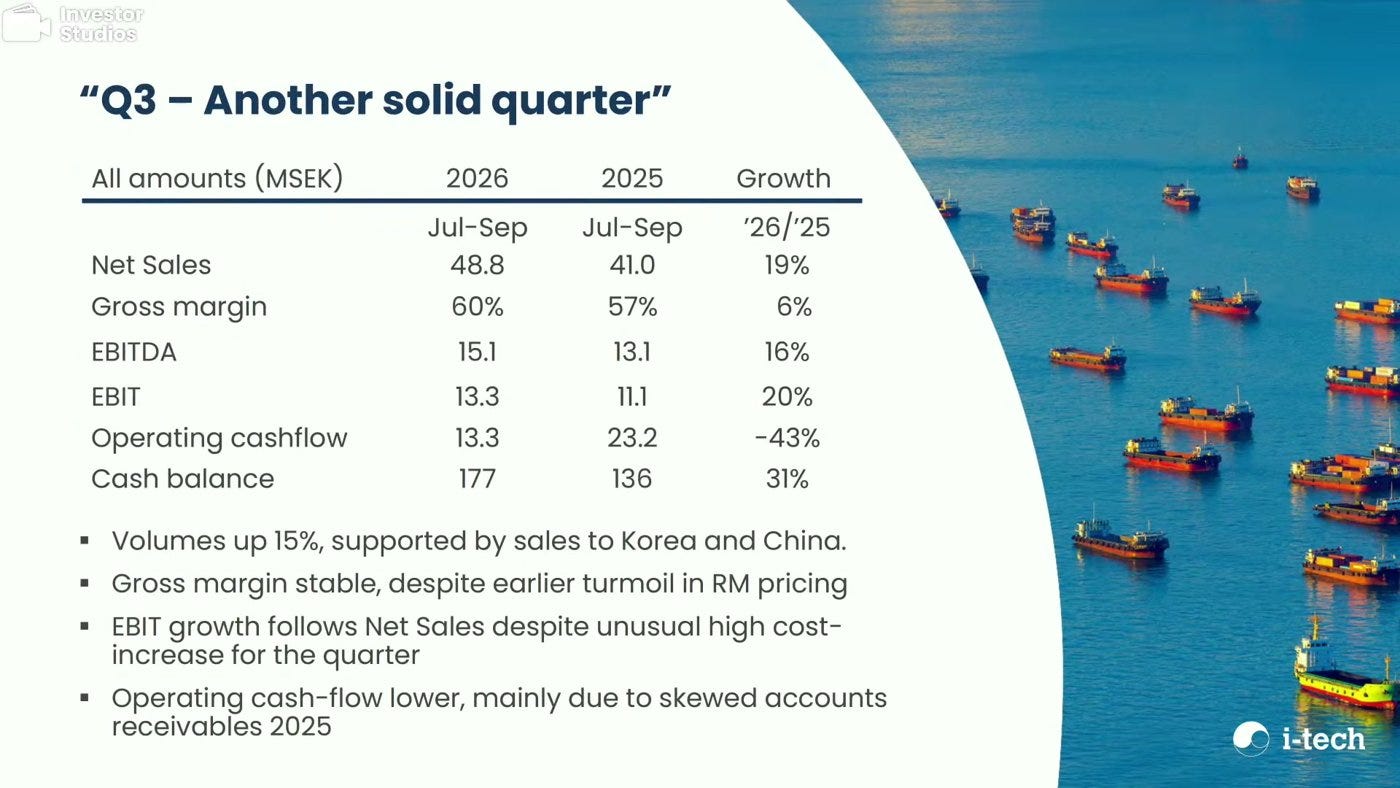
Cash at the end of September was up +30.6%. The money is there.
Operating margin stayed flat at 27% despite 19% sales growth and a better gross margin. That’s the cost side pushing back. Other external costs rose on the two new technology deals: the full initial purchase consideration for the acquired biologically derived technology was expensed in the period, and the period also carries the full annual minimum license fee on the licensed technology. Personnel costs rose with three added FTEs, and SEK 5.5m per quarter was confirmed on the call as roughly the new run rate. EU re-registration costs continue, at a lower level than last year.